📰 Curated Industry Article
This is a summary of a full article from a trusted insurance publication. Click “Read Full Article” below to read the complete story.
On October 7, 2026, a massive cyberattack struck Japan.
The incident, as of this writing, impacted 495 companies, compromising millions of files containing personal and financial information. In the same month, France was hit. This time it was numerous supermarkets, some of whom had outdated, internet-exposed, control panels running their refrigeration units.
In foodie France, one can only imagine the delicacies that had to be disposed of once those refrigerators were knocked out.
There are some who say that, given the power that A.I. brings to the scamming game, that we might be in for some cyber worries that could dwarf previous incidents. Now couple that thought with the reality that we have a softening (soft?) cyber insurance market on our hands. Some do think, as it was whispered at the recent WSIA meeting in San Diego, that those bringing capacity into the cyber insurance market with rates being lower, and danger being so nigh, that some owners of risk transfer capital might be in for some rude shocks.
That’s just one concern that has to be on the minds of insurance carrier underwriting leaders. As we honor our class of 2027 Risk & Insurance Executives to Watch, we should do so with a degree of compassion, as they have a lot more to think about then “just” cyber.
It would take a strong jerk of the steering wheel to steer this piece away from the topic of Artificial Intelligence, so I’m not going to attempt it and risk injury.
Carrier execs are also talking about A.I. as it is changing the pace of submissions. Armed with A.I., brokers are getting the details of their coverage requests to carriers faster. Carriers know that brokers want a swift response. The question then becomes, to what degree is this increased pace of business going to undermine underwriting discipline? We’re not done with A.I. yet. We also know that plaintiffs’ attorneys are using A.I. to parse the policies of insureds and insurers to find language vagaries that could be turned into vulnerabilities. And insurers are using A.I. to fine tune those very policies and better gird them against attacks from clever people and pretty clever machines.
My favorite feature in good old Mad Magazine was Spy Vs. Spy. Now it’s A.I. versus A.I.
The executives we feature in our annual Executives to Watch issue, which publishes each November, are largely nominated by their companies. We like that, because we like to have the cooperation of the insurance carriers in writing about their executives. There’s a whole host of risks and exposures that we have not mentioned in this introduction, but all know there are plenty of them.
All the more reason to wish our Executives to Watch the best of luck. And that goes for all of their peers and colleagues. &
The 2027 Executives to Watch
Alex Wells, CEO of Zurich U.S.
Amy Gross, general manager, head of North America Construction, Liberty Mutual
Duncan Ellis, Executive Vice President of Client Engagement, Starr
Gordon Browne, global head of specialty, AIG
Yue-Ling Fong, regional head of product development, Allianz Commercial, N. America
Kevin Sullivan, Head of Property Reinsurance | East Re Insurance, LLC, an AmTrust Company
Libby Benet, CEO, Risk Advisory, AXA XL
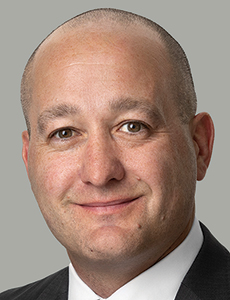
Matt Westhoff, President, Commercial Insurance, QBE North America
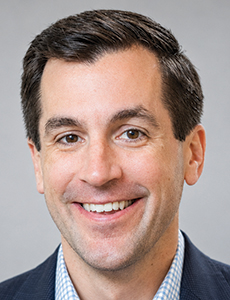
Stephen Screen, head of alternative placement solutions, global specialty business, The Hartford
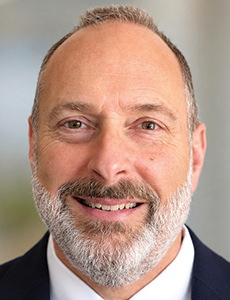
Todd Zeiter, Chief Underwriting Officer, The Doctors Company
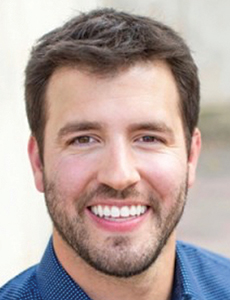
Tyler Ahrenhold, head of construction and Inland Marine, MSIG USA
Sean Ringstead, Chief Scientist and Executive Vice President, Chubb
The post Introducing the 2027 Executives to Watch appeared first on Risk & Insurance.
💡 What This Means For You
[securelife_dynamic_insight]
SECURELIFE INSURANCE
Secure Peace of Mind for You and Your Loved Ones
We provide comprehensive solutions including life insurance, mortgage protection, and annuities tailored to your needs.
📰 This article is sourced from a trusted insurance industry publication. SecureLife Insurance shares this for informational purposes only. Always consult a licensed advisor for personalized guidance.